
The usual caveat: I’m not a lawyer and this isn’t legal advice. What follows is statutory text and arithmetic, and I’ve pointed at the sources so you can check me. If I’ve gotten something wrong, tell me. That’s the whole point of writing it down.
Here are two sentences from the same act of the Illinois General Assembly, passed on the same night, effective on the same day.
The first creates the Targeted Advertising Services Tax. It imposes a tax of 10% of the gross receipts from targeted advertising services provided in Illinois, for any business with more than $1 million of those receipts over the prior twelve months.
The second is Section 3-20(a) of the Digital Asset Tax Act. It imposes a tax at the rate of 0.2% of the value of the digital asset to which the activity relates.
Read those again and notice what changed. It isn’t the rate. It’s the thing the rate is applied to.
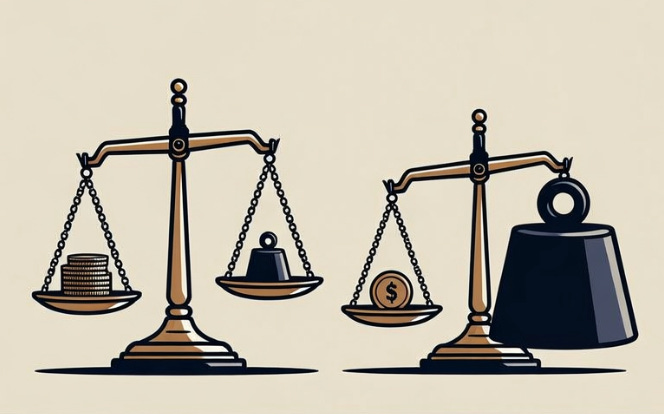
The advertising tax is measured against money a company actually received. The digital asset tax is measured against the size of the thing you moved, whether or not anyone received anything close to it.
Both provisions are in Public Act 104-468. Both take effect January 1, 2027. Somebody wrote one of them the way service taxes are ordinarily written, and then wrote the other one a way no state has written a tax before.
First, the part where I agree with the drafters
Taxing a service by taking a percentage of what the provider charges is completely normal. It isn’t a loophole and it isn’t generous. It is simply how this is done, in Illinois and nearly everywhere else.
Illinois taxes intrastate telecommunications at 8.65% of the gross charge for the service. The retail sales tax runs against the selling price. The advertising tax in this same bill runs against gross receipts. In each case the state takes a slice of a payment that actually happened, which means the tax scales with the business being done and can never exceed it.
I want to be clear that this is not a complaint about the 10% advertising tax. That tax has serious problems of its own; a court in Maryland struck down that state’s version last month, and I’ll come back to that. But whatever else is wrong with it, it is measured against something the taxpayer received.
That’s the whole comparison. The General Assembly demonstrated, in this bill, that it knows how to write a digital-services tax with a conventional base. Then it didn’t.
What that difference costs
Say you hold $50,000 of Bitcoin with one platform and move it to your account at another. No sale. No gain. No change in owner. You are moving your own money between two places you control, which is a taxable “transfer” under Section 3-15, because that section defines transfer to include moving an asset from one account or storage of a customer to another account or storage of the same customer.
Suppose the platform charges you a flat ten dollars to do it.
The tax is 0.2% of $50,000. That’s $100, ten times the fee you paid for the service being taxed.
Now run the advertising tax the same way. A platform that collects $50,000 in targeted advertising receipts owes 10% of $50,000, which is $5,000. That is a lot of money. It is also, unmistakably, a share of revenue the company took in.
One tax takes a slice of what a business earned. The other takes a multiple of it.
This is not my inference. The trade associations that sued Illinois on August 21 built a claim around it, pointing out that other tax provisions in the same omnibus are structured as a percentage of what the provider charges, and that this one is not. Their filing states that the bundling rule can produce a tax of 0.6% on each side of a trade, and that the resulting tax will sometimes exceed the entire fee the broker charged, particularly for custody and transfers, where fees are smallest. They also make the point that a platform may charge similar amounts to move ten dollars of Bitcoin and a million dollars of it, while the tax on the second is thousands of times larger.
If you read the post from a few weeks back about one purchase generating three taxable events, this is the other half of that problem. That post was about how many times the tax fires. This one is about what it fires at. The two compound: multiple events, each measured against the full value, none of them measured against the fee.
Why this is a legal question and not just an unfair one
I said in July that the strongest Illinois-law challenge is the Uniformity Clause, and I still think so. But the measurement problem opens a different door, and it’s worth understanding because the state will have to answer it.
When a state taxes activity that crosses state lines, the tax has to be fairly apportioned. Part of that test asks whether the state has reached beyond the portion of value fairly attributable to economic activity inside the state. A tax on brokerage services that is calculated against the value of the customer’s assets rather than the price of the services is, at minimum, going to have to explain what Illinois did to create that value.
There’s a second line of attack too. Courts weigh whether the burden a state law places on interstate commerce is excessive compared to the local benefit. A tax that can exceed the entire revenue from the transaction it taxes is an unusual place to start that argument from.
I’m not going to tell you how a court will rule. Nobody knows, and two cases are pending in Sangamon County right now with no hearing date. What I’ll say is narrower: the state has to justify the base, and the same bill makes the justification harder, because the legislature showed on those pages what it thinks a normal digital-services tax looks like.
What I’m not claiming
Not that the state can’t tax digital asset services. It can.
Not that 0.2% is a shocking rate. Standing alone it isn’t.
Not that the advertising tax is a good law. I don’t think it is.
The claim is one thing only: the Digital Asset Tax Act measures its tax against the wrong number, and we know it’s the wrong number because the General Assembly used the right one a few articles earlier in the same act.
The fix, and the honest cost of it
Change what the rate applies to. Measure the tax against the consideration the broker receives for the activity, instead of the value of the asset. That is a one-line amendment to Section 3-20(a).
It doesn’t solve everything. It doesn’t define “broker.” It doesn’t fix the sourcing rule, or say when value is measured, or address the fact that felony penalties attach on January 1 to rules that don’t exist yet. Those are separate problems and I’ll keep writing about them.
But it takes the single most disproportionate feature of this tax and replaces it with the structure Illinois already uses everywhere else.
Here’s the part I should say plainly rather than let someone else say it for me: a fee-based tax raises less money. That’s a real tradeoff and pretending otherwise would be dishonest. My answer is that a tax the state can actually defend and administer, raising less, is worth more than a larger number attached to a statute now facing two constitutional challenges and a repeal bill. The state will spend real money defending this base. It could spend none defending the other one.
And this is the kind of change a legislator can make without conceding anything. It isn’t repeal. It isn’t an admission the tax was a mistake. It’s a technical correction that makes the law look like the rest of the revenue code.
The ask
Write your own State Representative and ask for the base to be fixed. Find yours with the General Assembly’s Find My Legislator tool. Four sentences does it:
I’m a constituent in [town]. I’m writing about the Digital Asset Tax Act, which takes effect January 1, 2027. It taxes 0.2% of the full value of a customer’s digital assets rather than a percentage of what the broker charges — so on an ordinary transfer the tax can be several times the fee for the service, which is not how Illinois measures any other service tax, including the targeted advertising tax in the same bill. I’d ask you to support amending Section 3-20 to measure the tax against the consideration the broker receives.
[One sentence, in your own words, about why this matters to you.]
That last line matters. Identical form letters get counted once. A note that sounds like a person gets read like one.
If you want to be told when the Department of Revenue finally opens a comment period (the moment when this becomes a formal, on-the-record fight) subscribe. That’s what the list is for.
If I’ve misread either provision, write to me and I’ll correct it in the post the same day. The advertising tax figure and the Section 3-20 language are both worth checking yourself; I’d rather you did.
The Illinois Bitcoin Council is a nonpartisan 501(c)(6) nonprofit. This is educational commentary, not legal or tax advice.